

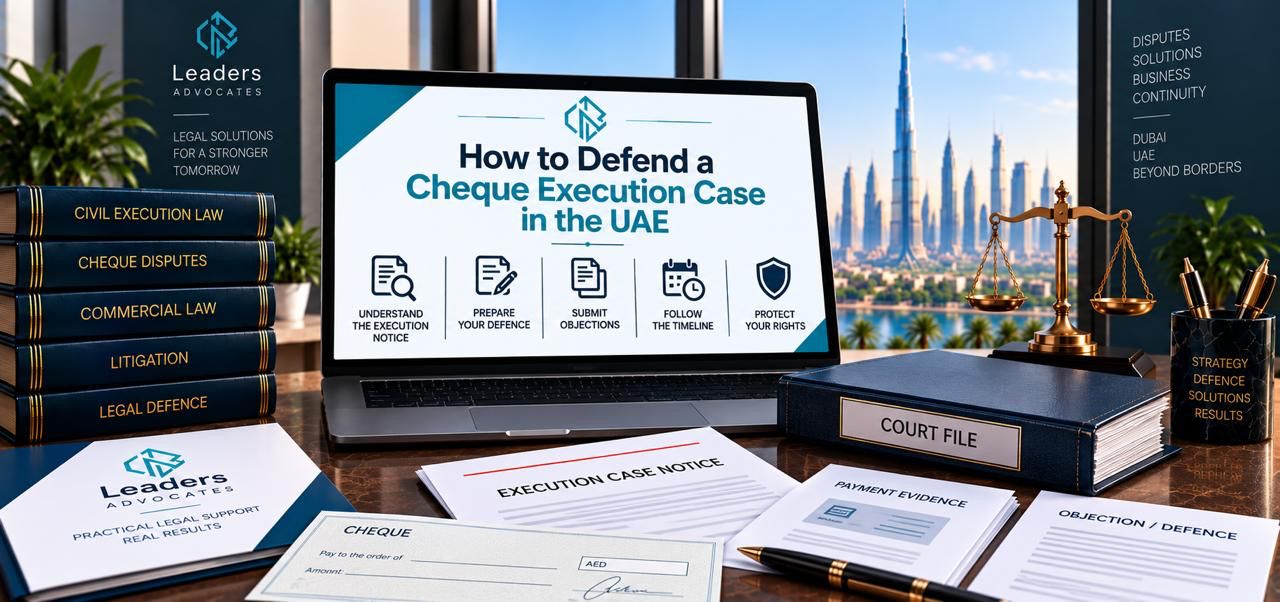
An execution notice arrives for a cheque you believe has already been paid, was used only as security, or contains an error. The notice may also raise immediate concerns about bank accounts or travel. Knowing how to defend a cheque execution case in the UAE starts with identifying the cheque, the bank’s return reason, and the deadline in the file.
Quick Answer
Check whether the cheque qualifies for direct execution, then raise any valid defense through the proper procedure with evidence. Review attachments and travel restrictions separately, and consider a written settlement where the debt is owed. Act within the time stated in the notice.
Obtain the execution notice and cheque records, compare the claim with your payment and contract documents, and seek advice promptly. Identify the specific objection and the evidence supporting it. Keep any request about enforcement measures distinct from the dispute over the amount or underlying obligation.
The Legal Basis for Cheque Execution
To defend a cheque execution case in the UAE, first confirm whether the cheque qualifies under Article 667 of Federal Decree-Law No. 50 of 2022. That covers cheques returned for lack of or insufficient funds and, under a 2023 unification principle, account closure. Cheques returned for other reasons generally do not.
Then raise objections through the execution procedure in the Civil Procedure Law where grounds exist, for example payment, forgery, alteration, or a time bar under Article 670. Arguments about the underlying deal, such as a security cheque that was never triggered, need strong evidence and may require separate proceedings. Payment, settlement or acceptable security can lead to release of travel bans and attachments.
Read the Cheque Execution Notice Carefully
- Which cheque is being enforced, and for what amount?
- What return reason did the bank record?
- When was the cheque presented and returned?
- What deadline has the notice given you?
The Civil Procedure Law gives the debtor a short period after notification to pay before compulsory measures begin. Use it to take advice, not to wait.
Build a working file from the notice
Keep the notice exactly as received, including information about when and how it reached you. Identify the file reference, creditor, cheque number, and amount claimed. Put the cheque copy and bank return record beside it. If an attachment is missing or unreadable, flag that promptly when taking advice rather than filling the gap from memory or an earlier collection message.
Compare the cheque details with your own records. You may have issued several cheques to the same person, so make sure the objection concerns the instrument actually being enforced. Note any payment made against that obligation and any written agreement reached since delivery. An accurate starting file reduces the risk of preparing a response to the wrong cheque or an outdated balance.
Just Received a Cheque Execution Notice?
Don’t wait out the deadline. Send us the notice on WhatsApp now and we’ll tell you exactly where you stand.
Check Whether the Cheque Qualifies for Direct Execution
A cheque returned for insufficient or no funds can be executed directly under Article 667. Account closure also permits direct execution under the 2023 unification principle.
A signature mismatch or technical defect generally does not permit direct execution; the holder needs a payment order or claim. An account freeze is treated differently from account closure in case law.
If the cheque does not fall within Article 667, that may be a strong ground to challenge the execution.
Read the return reason as recorded by the bank. Keep the wording intact when describing it to your adviser. An account closure, an account freeze, and a signature issue should not be grouped together simply because each resulted in nonpayment. The question is whether the particular cheque and return reason support the execution route being used.
If you believe the return record is incomplete or has been misunderstood, identify the document needed to explain the issue. Keep any related bank correspondence with it. Leaders Advocates’ litigation lawyers in Dubai can review the execution papers and assess whether the stated objection concerns eligibility for direct execution or a different aspect of the dispute.
Identify Your Defense to Cheque Execution in the UAE
- Payment: you already paid the amount by transfer or cash, with proof.
- Forgery or alteration: the signature, amount or payee was forged or changed.
- Time bar: the holder’s recourse claim is beyond the period in Article 670, which you must raise.
- Wrong party: you are not the drawer or were not personally bound.
- Security cheque: the obligation it secured was never breached. This needs clear evidence and may require separate proceedings.
An objection to cheque execution without evidence rarely succeeds. Bring receipts, bank records, the underlying contract and correspondence.
Connect payment records to the cheque being enforced
For a payment defense, identify the amount, date, recipient, and transaction reference. Explain how the payment relates to the cheque in the execution file, especially if there were several dealings between the parties. Keep receipts and correspondence confirming what the payment covered. A transfer shown on a bank statement is more useful when its connection to the claimed obligation is clear.
Where only part of the balance was paid, state that accurately and show your calculation of what remains disputed. Keep the original amount, each payment, and any claimed adjustment separate. Do not describe a partial payment as full settlement unless the supporting agreement says so. Give your adviser both the payment evidence and any response from the holder.
Explain a security cheque or document concern precisely
If you rely on the cheque’s security purpose, provide the contract and the messages explaining when it could be used or should be returned. Identify the obligation it secured and the evidence that it was completed or never breached. A general description of the cheque as security does not explain the disputed condition or show what actually happened in the relationship.
For alleged forgery or alteration, point out the specific entry or signature you dispute and preserve the copies and records available to you. Explain the basis of the concern without rewriting or marking the only copy you hold. For a wrong-party argument, provide the documents showing the capacity in which the cheque was issued. Each defense requires its own factual explanation.
If limitation is raised, organize the cheque dates and related records for review under Article 670. Avoid relying on an approximate statement that the cheque is old. Leaders Advocates’ civil lawyers in Dubai can assess the underlying contractual dispute and the evidence relevant to the defense being considered.
Have a Real Defense But No Idea Where to Start?
Payment proof, a security agreement, or a forged signature can all change the outcome. Message us on WhatsApp and we’ll map your evidence to the right defense.
Manage Attachments and Travel Bans
Once the notice period passes, the holder can ask the execution judge for measures such as attachment of bank accounts, property or vehicles. Where the debt is at least AED 10,000 and the conditions in Articles 324 to 327 are met, the holder can also ask for a travel ban. To lift a travel ban in a cheque case, the debtor typically pays, settles or provides security acceptable to the court. Salary attachment is subject to legal limits, and certain assets are protected.
Identify the measure you need reviewed
Keep any attachment or travel-ban paperwork alongside the execution notice, with the relevant dates. Explain whether you are challenging the debt, seeking review of a particular measure, or proposing security. These concerns may arise together, but the factual basis of each should be clear. A general statement that the cheque is disputed does not explain what relief you are asking the court to consider.
Where salary or an asset protection is relevant, gather the documents showing the nature of the affected funds or property. If payment or security is proposed, provide the details of what can actually be offered. Discuss the response through the legal process instead of assuming an informal conversation with the holder has resolved the status of the measure.
Consider a Written Cheque Settlement
If the debt is owed, settlement is often the most practical defense. A written settlement should cover the payment schedule, what happens to the original cheque, withdrawal of the execution file and release of any travel ban or attachment. Paying or settling can also end criminal proceedings for the cheque offenses within the stages the law allows.
A practical settlement discussion begins with a reconciled balance. Check the amount in the file against payments already made and identify any difference before agreeing a schedule. Keep the payment dates realistic and the method clear. Where the parties have exchanged several proposals, ensure the final written version reflects the agreement actually reached rather than an earlier offer.
Address the cheque and the execution file expressly in the written terms. Record what is to happen to the original instrument, the withdrawal of the file, and any existing attachment or travel ban. Retain payment evidence and correspondence about the agreed follow-up. A payment schedule alone may leave the parties unclear about those practical steps even when the amount has been agreed.
Leaders Advocates’ debt recovery legal services in Dubai can help assess the claimed balance and proposed repayment terms in the context of the execution dispute. Explain your position as the debtor and provide the current court papers so the discussion addresses the actual file.
Avoid Actions That Create Further Cheque Liability
Some reactions create new problems. Closing your account, emptying it before other cheques are presented, or giving the bank a stop order outside the permitted cases can fall within Article 675. That article carries imprisonment of six months to two years and/or a fine of at least 10% of the cheque value, with a minimum of AED 5,000 and a maximum of twice the value.
Before reacting to the notice, list any other cheques still outstanding and raise them with your adviser. Keep bank correspondence and instructions already given. If an account change has already occurred, provide the date and details accurately. Omitting those facts can leave the advice focused on the execution objection while missing a separate concern about your conduct involving other cheques.
Worried About Criminal Exposure Over a Cheque?
Closing an account or stopping a cheque the wrong way can create new liability. Talk to us on WhatsApp before you take any action.
Options When the Debt Is Unmanageable
Where the debts are unmanageable, individuals who are not traders can consider Federal Decree-Law No. 19 of 2019 on Insolvency. Companies and traders fall under Federal Decree-Law No. 51 of 2023. These processes are court-supervised and can affect how individual enforcement proceeds.
Prepare a complete picture of the debts and pending proceedings before discussing these routes. Identify the obligations, payment difficulties, and existing enforcement measures, and collect the supporting financial records. Explain whether the debtor is an individual, trader, or company. This gives the adviser the information needed to assess the relevant framework rather than treating inability to pay as a documentary defense to the cheque itself.
Common Mistakes
- Ignoring the execution notice.
- Objecting without documentary evidence.
- Relying on a verbal agreement that the cheque was only security.
- Closing accounts or stopping other cheques in response.
- Settling without retrieving the original cheque.
Faris Raian and the team at Leaders Advocates can assess your specific situation.
See also our guide to clearing a bounced cheque case in Dubai, our overview of whether a bounced cheque is a criminal offence in the UAE, and Mondaq’s guide to choosing the best cheque bounce lawyer in Dubai. Follow Leaders Advocates on LinkedIn or Leaders Advocates on Facebook for more UAE legal updates.
FAQs
Facing a Cheque Execution Case in the UAE?
Don’t miss your deadline. Message Leaders Advocates on WhatsApp now for a fast, confidential review of your case.