

A bank can reject a cheque for many reasons. The holder may see only that payment failed and assume every case follows the same legal route.
That assumption can waste time. The bank’s exact wording determines whether the holder can seek direct execution, needs a corrected cheque, or must rely on the underlying debt.
Quick Answer
When a bank rejects a cheque in the UAE, the recorded return reason controls the next step. A cheque returned for no or insufficient funds can be an executive instrument under Article 667 of Federal Decree-Law No. 50 of 2022.
A closed account may also support the execution route under the 2023 unification principle. Signature problems, technical defects, a post-dated cheque, a stop order, or a frozen account require separate review.
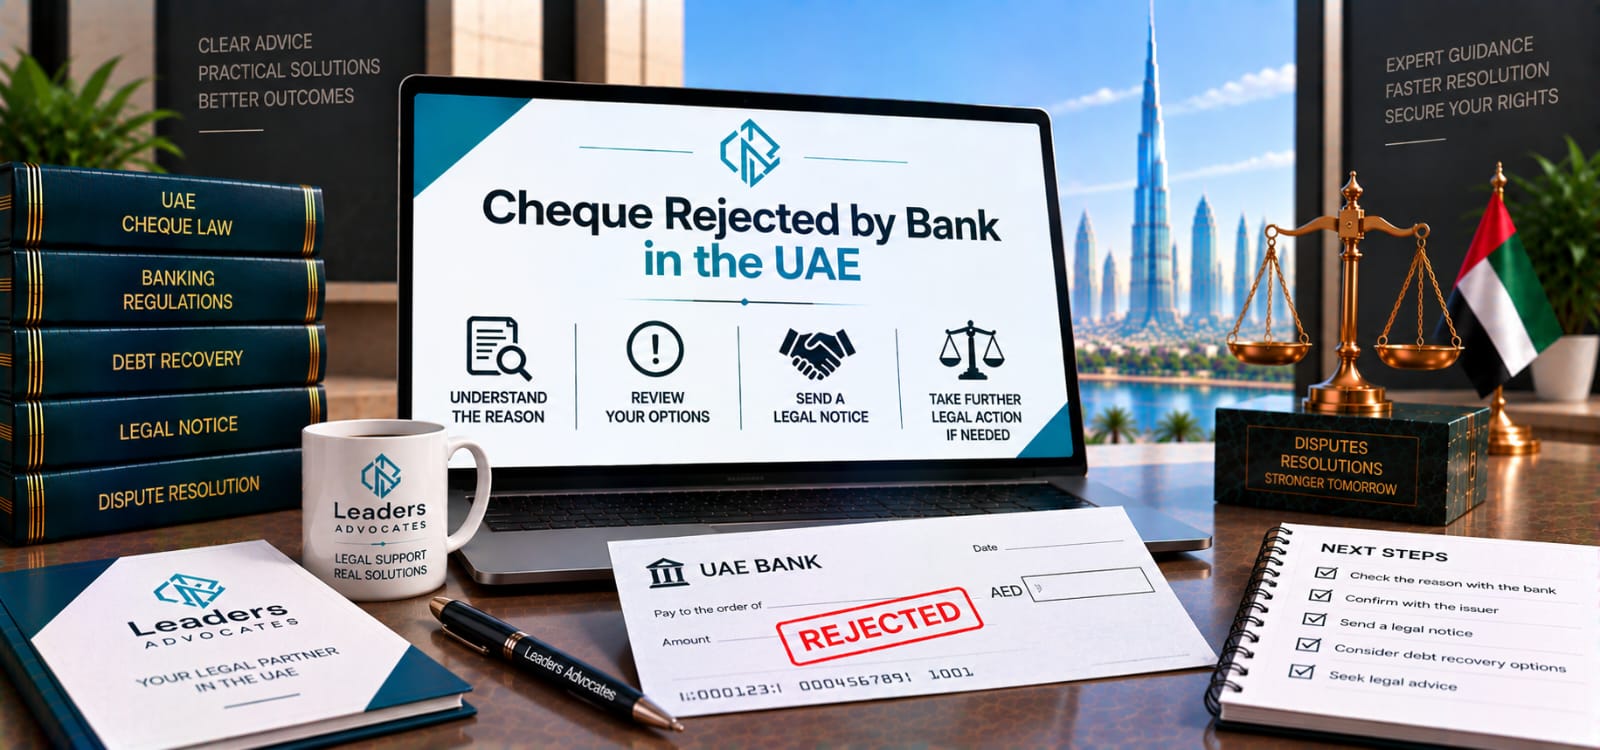
Keep the original cheque, formal bank memo, partial-payment certificate, contract, invoices, and communications. Do not assume every return is criminal. Choose the remedy after matching the bank’s wording to the current law and the underlying debt.
Obtain the formal return memo and protect the original cheque. Record the presentation date, return reason, unpaid balance, and any partial payment.
Then choose the next step. It may be redeposit, correction, a written demand, settlement, execution, a payment order, or an ordinary claim.
Cheque Rejected by Bank UAE
Start by reading the bank statement line by line. No funds, insufficient funds, a closed account, a signature issue, a stop-payment instruction, a future date, and a frozen account are different facts.
Do not describe the case as a bounced cheque only. Use the precise return reason in every notice and filing.
Keep the bank’s date and stamp visible. A clear record reduces later argument about presentation and dishonor.
Get the Formal Bank Record
Article 663 allows dishonor to be proved by a dated statement from the drawee bank. The statement should identify the presentation day and appear on the cheque as required.
Ask the bank for any available dishonor certificate or related record. Keep app messages, emails, deposit slips, and SMS notices as supporting material.
An oral explanation from a teller is not enough. The legal route should match the formal record.
No or Insufficient Funds
Article 667 provides that a cheque marked unpaid for lack of or insufficient funds is an executive document. The holder may seek compulsory execution for the whole unpaid amount or the remaining balance.
This route can avoid an ordinary merits case on the same instrument. The execution request still needs the correct claimant, debtor, amount, original cheque, and bank notation.
Court measures are not automatic. Attachment, travel restrictions, and other requests remain subject to the applicable procedure and judicial decision.
Bank Rejected Your Cheque?
Send us the return reason on WhatsApp now and find out in minutes whether you can go straight to execution.
Partial Payment
If the account contains less than the cheque amount, the bank must pay the available balance unless the holder refuses. The bank records the payment and provides the documents needed to pursue the remainder.
Accepting part can reduce the outstanding claim. The holder should update the demand and filing to avoid claiming the full face value after receiving money.
Keep the marked original cheque and partial-payment certificate. They support the calculation of the remaining balance.
Closed Account
A 2023 unification principle treats a cheque returned because the account was closed as an execution instrument for Article 667 purposes. The facts still need review.
Account closure may also raise criminal exposure under Article 675 in the circumstances defined by law. Civil recovery and criminal responsibility are separate questions.
Confirm when the account was closed and who controlled it. Do not assume the same result for every account-status problem.
Signature Differs or Is Irregular
A signature return generally falls outside the natural Article 667 route because the bank has not certified insufficient funds. Ask for correction or payment first.
If the drawer deliberately signed the cheque to prevent payment, Article 675 may apply. Intent must be proved from the evidence.
An honest error usually leads to a replacement cheque, payment order, or civil claim on the underlying transaction.
Stop-Payment Instructions
A drawer cannot stop payment simply because a commercial dispute has arisen. The law permits objection to payment only in limited circumstances, such as loss of the cheque or the holder’s bankruptcy.
An improper payment-stop instruction is one of the acts addressed by Article 675. The provision can carry imprisonment from six months to two years and/or a fine within the statutory range.
The drawer should raise a contract dispute through the proper legal channel. The holder should preserve the bank record and the underlying documents.
Dealing With a Stop-Payment or Signature Dispute?
These returns move fast and get complicated. Message us on WhatsApp now and get a clear next step today.
Post-Dated Cheques
A cheque presented before its written date may be returned because payment is not yet due through the normal banking process. Record the correct date and ask the bank about re-presentation.
Do not confuse a future date with insufficient funds. The bank’s return reason and timing matter.
Keep proof of the first attempt. Re-present promptly when the cheque becomes payable, while also monitoring legal deadlines.
Stale, Altered, or Technically Defective Cheques
A bank may reject a cheque because of a date issue, mismatch between words and figures, alteration, missing detail, damage, or another technical defect. These returns may require correction rather than Article 667 execution.
Ask the drawer for a valid replacement or direct payment. Record the request and a clear deadline.
If correction fails, use the contract, invoice, loan, or settlement to assess a payment order or ordinary claim.
Frozen Accounts
A frozen account is not automatically the same as a closed account. The reason for the freeze, the authority behind it, and the account status require review.
The holder should ask the bank for the precise return wording. Counsel can then determine whether execution on the cheque or a claim on the debt is more suitable.
Avoid assuming that a temporary freeze proves criminal conduct by the drawer.
Criminal Liability Is Not Automatic
Issuing a cheque without enough funds is no longer, by itself, the former automatic criminal offense under the reformed framework. Many ordinary dishonor cases now proceed through civil execution.
Criminal liability remains for defined conduct, including certain stop-payment instructions, account closure or depletion, deliberately obstructive signing, and forgery.
A complaint must match the statutory facts. Do not describe a payment dispute as a crime without evidence of the required act and intent.
What the Holder Should Do
Take these steps in order:
- Obtain the formal bank return record.
- Keep the original cheque secure.
- Confirm the unpaid balance.
- Preserve the contract and performance evidence.
- Notify the drawer in writing.
- Assess execution, correction, settlement, or claim.
- Check the debtor’s identity and reachable assets.
Do not hand the original back before payment or a protected settlement. Use working copies for correspondence.
What the Drawer Should Do
Read the bank reason immediately. If the problem is genuine error or temporary funding, correct it and document payment.
Do not issue a payment-stop instruction simply because the underlying deal is disputed. Obtain advice on the contract dispute instead.
If execution has started, respond to the exact instrument, balance, and requested measures. Ignoring the file can increase cost.
Preserve the Underlying Debt Evidence
The holder may need the original transaction if the cheque cannot use the direct execution route. Keep the agreement, invoice, delivery record, account statement, and admissions.
For a company cheque, confirm the legal entity named on the account. A manager or shareholder is not automatically personally liable.
Reconcile all credits and partial payments. The claim should state one accurate amount.
Not Sure What Evidence You Need?
Send your cheque, bank memo, and contract on WhatsApp — we’ll tell you exactly what’s missing and what to do next.
Demand and Settlement
A written demand should identify the cheque, return date, bank reason, underlying debt, and deadline. It should not make unsupported criminal threats.
A settlement should identify payment dates, security, default consequences, and treatment of the original cheque. The release should take effect only as agreed.
When the account may soon be funded, a second presentation can be considered. It should not replace deadline tracking or a recovery plan.
Execution and Enforcement
For a qualifying Article 667 cheque, prepare the original instrument, bank notation, balance, party details, and required procedural documents. Confirm the execution court and current filing requirements.
Plan beyond the filing. The useful result is recovery against available assets, not only opening an execution file.
Ask for lawful asset-focused steps. No measure should be presented as automatic or guaranteed.
Related Success Story
Leaders Advocates publishes a debt recovery case involving successful loan recovery in Dubai. The Leaders Advocates Success Stories page contains the available summary.
That outcome depended on its own evidence and parties. It shows why a clean debt file and an enforceable recovery route matter.
Common Mistakes
- Treating every bank return as an insufficient-funds case.
- Returning the original cheque too early.
- Ignoring partial payment.
- Claiming the full amount after receiving funds.
- Assuming every bounced cheque is criminal.
- Using the wrong debtor name.
- Waiting without tracking presentation and claim periods.
- Filing without the underlying contract when it may be needed.
Final Takeaway
When a bank rejects a cheque in the UAE, the return reason decides the first legal step. Preserve the original and formal bank record before negotiating or filing.
Use Article 667 only when the instrument and bank notation support it. For other returns, correct the cheque or pursue the underlying debt through the appropriate civil route.
Relevant Legal Services
- Debt Recovery Lawyers in Dubai – for demands, settlement, cheque recovery, and enforcement strategy.
- Litigation Lawyer in Dubai – for execution applications, payment orders, civil claims, and challenges.
- Civil Lawyers in Dubai – for claims based on the underlying loan, invoice, contract, or settlement.
Follow Leaders Advocates on LinkedIn or Leaders Advocates on Facebook for more UAE legal updates.
Frequently Asked Questions
Had a Cheque Rejected in the UAE?
Don’t guess your next move. Message Leaders Advocates on WhatsApp now and get a clear, fast answer on execution, correction, or claim.