

The creditor needs a reliable timeline for cash flow, settlement, or business planning. Yet UAE debt cases do not have one standard completion date.
The route, dispute, service, expert evidence, appeals, insolvency, and asset searches can change the duration significantly.
Quick Answer
There is no fixed answer to how long does debt recovery case take UAE. A qualifying cheque execution or payment order may move faster because it can avoid a full merits trial. A disputed claim usually takes longer.
Time increases when service is difficult, documents need translation, an expert is appointed, appeals are filed, or insolvency begins. Enforcement may last longer than the court case because collection depends on reachable assets.
A lawyer can estimate stages after reviewing the documents, forum, debtor response, and asset position. Any estimate remains conditional on the facts and court process. Regular updates are essential.
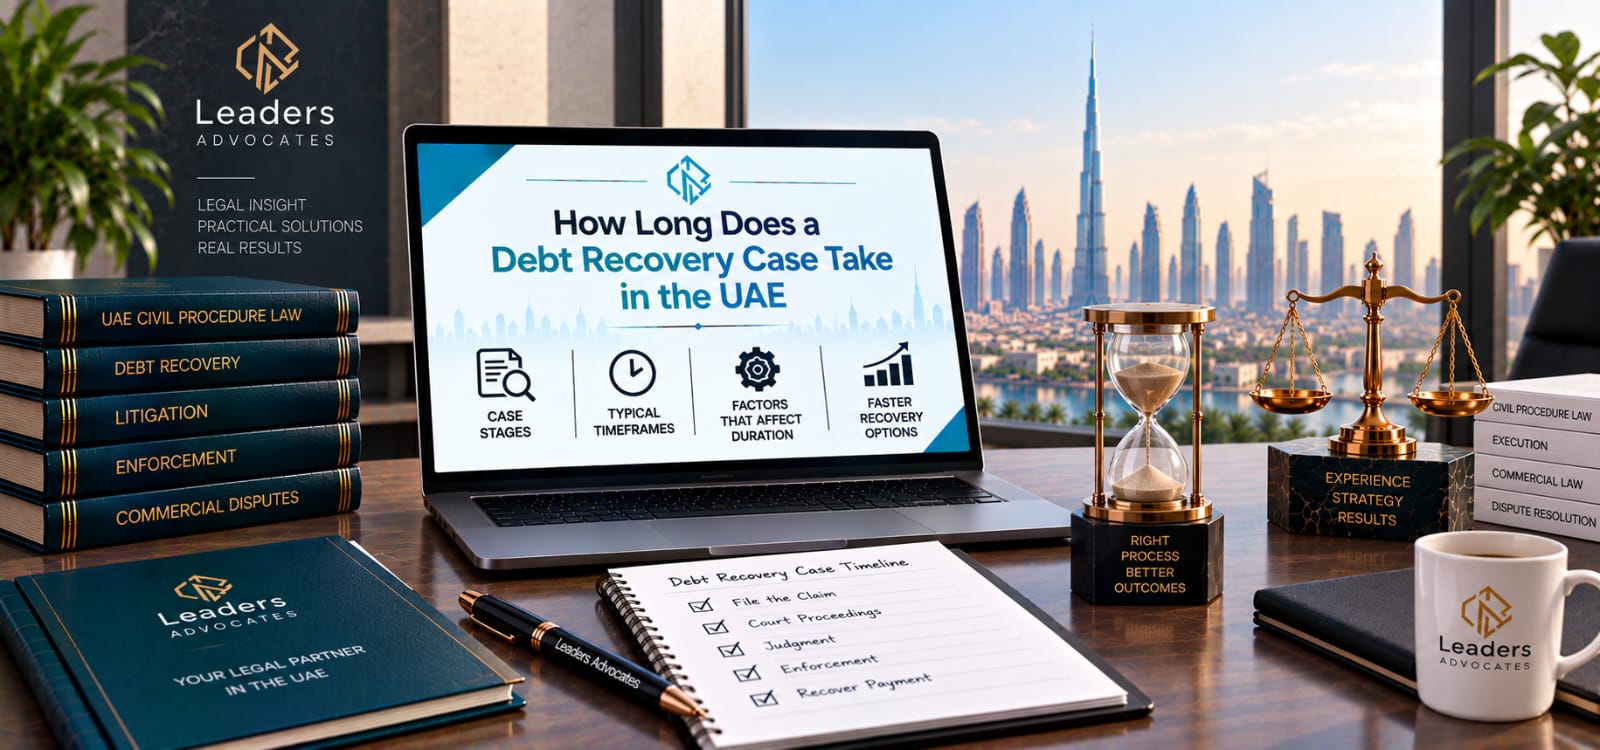
How Long Does Debt Recovery Case Take UAE?
A useful estimate should separate pre-action work, filing, service, merits, appeal, and execution. Each stage has different causes of delay.
- Demand and negotiation time depends on the notice and response.
- Conciliation may apply before filing in qualifying Dubai disputes.
- Service depends on accurate identity and address information.
- The merits stage depends on defenses, hearings, and expert work.
- Appeal timing depends on the judgment and applicable deadline.
- Execution depends on asset identification, objections, and sale procedures.
A short court stage can still lead to slow recovery. A judgment confirms liability but does not create assets.
Owed Money and Not Sure How Long Recovery Will Take?
Send your documents on WhatsApp now and get a realistic stage-by-stage timeline within minutes.
What Usually Moves Faster
Cheque execution can move directly to enforcement when Article 667 applies. The cheque and bank return documentation must support the route.
A payment order can be decided on documents where the debt is fixed, due, and evidenced. The creditor must first give at least five days to pay.
A settlement may end the dispute sooner than either route. Its practical value depends on payment security and the debtor’s capacity.
What Usually Takes Longer
- A dispute over goods, services, defects, variations, or calculation.
- A counterclaim or set-off asserted by the debtor.
- Court-appointed accounting or technical expertise.
- Incorrect party details or difficulty completing service.
- Missing certified Arabic translations.
- Appeals, enforcement objections, or competing creditors.
- Foreign parties, foreign documents, or assets outside the UAE.
A matter in DIFC, ADGM, arbitration, or another specialized forum follows its own timetable. The contract and entity records control that question.
Why Enforcement Can Take the Longest
Execution measures may target accounts, property, vehicles, shares, and third-party receivables. Each request requires processing and may produce objections.
Assets may already be secured, jointly owned, transferred, or insufficient. Sale procedures also take time and may involve valuation and priority questions.
For qualifying individuals, a travel ban may be requested under Articles 324 to 327. It is a protective measure, not payment itself.
Judgment Won But Payment Still Not Received?
Enforcement is where most delay actually happens. Message us on WhatsApp and we’ll map out the fastest route to your assets.
Legal Framework for Debt Recovery Timelines
The governing legal framework
Federal Decree-Law No. 42 of 2022 governs civil procedure in the federal framework. Local court systems and financial free zones may apply separate procedural rules.
Articles 143 to 150 regulate payment orders for certain fixed, due, and documented debts. The creditor must first demand payment and allow at least five days.
Federal Decree-Law No. 50 of 2022 governs commercial transactions. Article 667 treats a qualifying returned cheque as an executive instrument.
A cheque route depends on the return reason and supporting bank record. A signature dispute or other defense may require a different legal route.
Federal Decree-Law No. 51 of 2023 governs financial restructuring and bankruptcy. Once qualifying proceedings begin, individual enforcement may be stayed or controlled.
Commercial claims between merchants are generally subject to a five-year period when the debtor denies the claim. The starting point and interruptions require file-specific review.
Articles 324 to 327 of the Civil Procedure Law regulate travel-ban applications in qualifying debt matters. The debt threshold is AED 10,000, alongside other legal conditions.
A travel ban is not automatic. It requires a court application, supporting evidence, and satisfaction of the statutory conditions.
Practical Steps
Start with a legal and commercial assessment. Confirm the amount, the due date, the parties, the forum, and the debtor’s ability to pay.
- Reconcile the account and remove calculation errors.
- Confirm the debtor’s exact legal identity and current address.
- Review dispute-resolution, notice, and governing-law clauses.
- Send a focused written demand with a clear deadline.
- Choose negotiation, a payment order, cheque execution, arbitration, or an ordinary claim.
- Plan enforcement before spending heavily on litigation.
Settlement can be practical when it produces secured and realistic payments. Record the amount, schedule, default consequences, releases, and treatment of pending proceedings.
If litigation is required, file in the competent forum. Respond promptly to court directions, expert requests, translations, and service issues.
After judgment, open or continue execution without delay. Request asset measures based on reliable information and monitor the file actively.
Evidence and Documents Needed
A strong recovery file connects the legal obligation, performance, maturity, default, and amount. Each document should support one part of that chain.
- Signed contract, purchase order, facility agreement, or accepted terms.
- Invoices and a current statement of account.
- Delivery notes, completion certificates, or service records.
- Emails, messages, and written acknowledgments of the balance.
- Payment records, returned cheques, guarantees, and security documents.
- The debtor’s correct legal name, license details, address, and known assets.
Foreign-language documents usually need certified Arabic translation for onshore court use. Foreign documents may also require legalization or other authentication.
Keep originals when they exist. Preserve electronic records in their native form, including dates, sender details, attachments, and complete message threads.
Not Sure Your Documents Are Strong Enough?
Send us what you have on WhatsApp and we’ll tell you exactly what’s missing before you file.
Common Mistakes and Risks
- Using the wrong legal name or suing only a trade name.
- Waiting while limitation or appeal periods continue to run.
- Relying on invoices without proof of delivery or acceptance.
- Sending an unclear demand that does not support the intended procedure.
- Assuming a judgment automatically produces payment.
- Ignoring arbitration, DIFC, ADGM, or other jurisdiction clauses.
- Accepting a payment plan without security, default terms, or written acknowledgment.
A procedural shortcut can waste time if its legal conditions are missing. The correct route should follow the evidence, not the creditor’s preferred timetable.
How a Lawyer Can Help
A debt recovery lawyer can test the evidence, identify the correct defendant, and select the procedure that fits the documents.
Counsel can draft the demand, calculate the claim, address jurisdiction, and prepare Arabic court filings. Counsel can also respond to defenses and expert questions.
During enforcement, a lawyer can request lawful asset measures, follow third-party responses, address objections, and evaluate settlement against the expected recovery.
Legal advice cannot guarantee collection. Its value is reducing avoidable procedural risk and aligning the strategy with reachable assets.
Costs, Court Fees, and Commercial Decisions
A legally valid claim may still be commercially unattractive. The creditor should compare the debt, likely fees, court charges, translation costs, expert costs, and expected enforcement return.
Court fees differ by forum, claim value, and procedure. Current fees should be confirmed with the competent court before filing.
A debtor may also have secured creditors or earlier attachments. Priority and available equity can affect whether a successful claim produces a meaningful payment.
For a portfolio, use written authority levels for settlement discounts, installment terms, and litigation spending. This prevents inconsistent decisions and unnecessary delay.
Settlement should be measured against realistic net recovery, not only the face value of the claim. Consider timing, security, enforcement risk, and the debtor’s continuing business value.
Jurisdiction and Forum Checks
Before any filing, review the jurisdiction clause, arbitration agreement, place of performance, debtor address, and licensing authority. These details can determine the competent forum.
Mainland courts, DIFC Courts, ADGM Courts, arbitral tribunals, and specialized committees follow different rules. A filing in the wrong forum can lose time and cost.
Where several forums appear possible, obtain a reasoned jurisdiction assessment. The focus keyword or commercial preference cannot replace the contract and procedural law.
Building a Realistic Case Timeline
A useful timeline contains ranges and assumptions. It should identify the expected forum, service method, likely defense, expert risk, appeal possibility, and enforcement plan.
Update that timeline after service, the first defense, any expert appointment, and judgment. New information can materially change the estimate.
Separate legal completion from cash receipt. A judgment date and a recovery date are rarely the same milestone.
Businesses should plan cash flow conservatively. Treat expected recovery as uncertain until funds are received and any settlement conditions are satisfied.
Ask counsel for the next procedural event, required client action, and main cause of delay. Specific reporting is more useful than a single promised completion date.
Keep decision-makers available for settlement authority and document requests. Client-side delays can extend expert work, negotiations, filings, and enforcement applications.
Relevant Legal Services
The appropriate service depends on the claim, the contract, the forum, and the enforcement position.
Relevant Success Story
See our debt recovery success stories for an example of how documented recovery work may progress.
Past results do not guarantee a similar outcome. Every matter depends on its own facts, documents, assets, and legal circumstances.
Follow Leaders Advocates on LinkedIn or Leaders Advocates on Facebook for more UAE legal updates.
Frequently Asked Questions
Final Takeaway
Debt recovery duration depends on the chosen route and the debtor’s response. Enforcement often controls when money is actually received.
Seek a stage-by-stage estimate based on the documents, forum, disputes, and assets. Review deadlines continuously as the case develops.
Ready to Start Recovering What You’re Owed?
Message Leaders Advocates on WhatsApp now for a fast, honest read on your debt recovery timeline.